

Cash Advance Now - PayDaySay
by PayDaySay
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
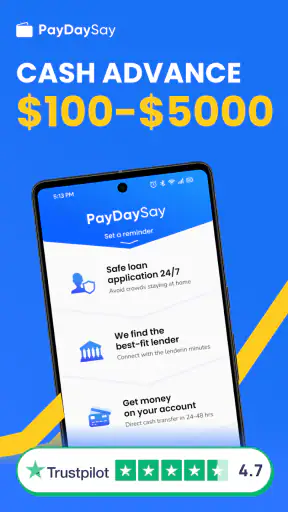
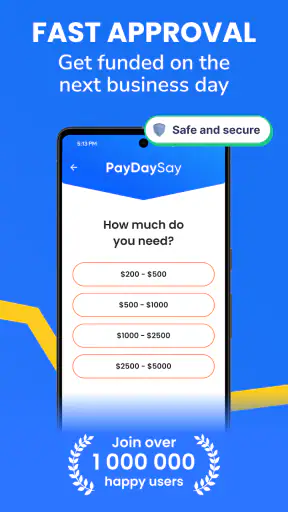
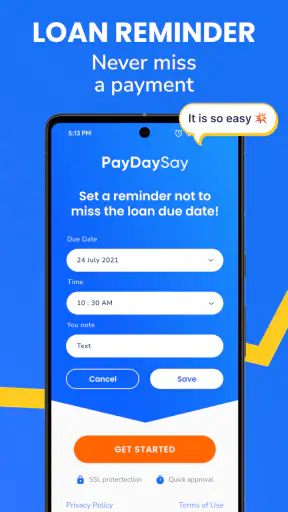
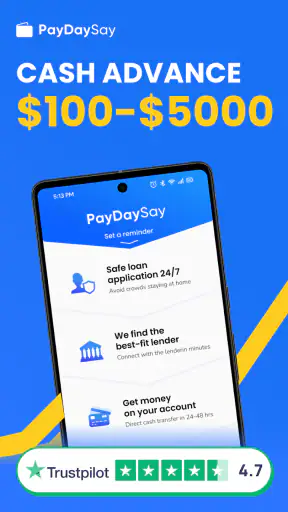
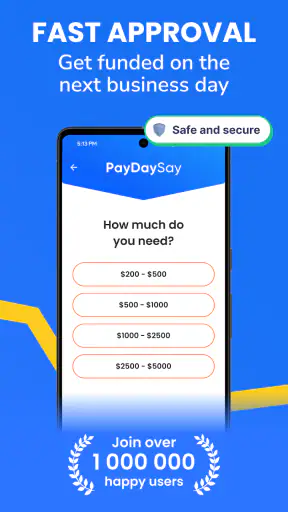
 Analysis by Getfullapps
When an unexpected bill lands before payday, the appeal of Cash Advance Now - PayDaySay is easy to understand. This finance app from PayDaySay is built around short-term access to borrowed money, and its store summary presents it as a way to request an instant payday cash advance. I approached it as a practical emergency-money tool rather than as a general budgeting app, and that distinction matters from the first screen.
The app is free to install, carries an Everyone age rating, and runs on Android devices using version 6.0 or later. That makes it accessible to a broad range of users, including people with older phones. It is also a relatively established listing rather than a brand-new experiment: the app was released on December 28, 2022, and has passed 100K installs. Its average rating is 4.6 from around 16K ratings, with around 773 written reviews, so there is enough public response to suggest that many people have found the basic experience useful.
How the app fits an emergency borrowing decision
My first impression is that PayDaySay is aimed at speed and simplicity, not at teaching personal finance. You do not open it because you want a detailed spending plan, investment dashboard, or long-term savings routine. You open it when a small gap between today and your next paycheck feels more urgent than a conventional lending process can accommodate.
That focus gives the app a clear purpose, but it also means I would not treat it as a replacement for a bank account or a complete financial safety net. A cash advance can solve a timing problem; it does not remove the underlying expense. The useful question is therefore not simply whether the app can help you borrow, but whether borrowing is sensible for the particular bill in front of you and whether repayment will leave enough money for essentials.
The free price is an important part of the value calculation. You can get the app without paying an upfront purchase fee, which lowers the barrier to checking whether it suits your situation. However, free installation should not be confused with free borrowing. The cost of any advance depends on the terms shown during the application process, so I would read every repayment amount, fee, and timing detail before accepting anything. The app’s download price tells me what it costs to access the software, not what a loan costs.
What I would check before requesting money
I would begin by deciding the exact amount needed rather than entering a hopeful maximum. If the immediate problem is a utility bill, transport expense, or necessary household purchase, I would write down that total first and avoid adding a cushion simply because the option is available. This small step prevents a fast application from turning a narrow cash shortage into a larger repayment obligation.
Next, I would inspect the complete offer rather than focusing on the headline amount. The practical details are the repayment date, the total amount to repay, any applicable charges, and the consequences of missing the schedule. Those details are more important than the promise of speed. If the repayment would consume money needed for rent, food, medication, or another fixed commitment, I would stop there and look for a safer alternative.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I would also make sure the information entered is accurate and consistent. A rushed application is a poor time to guess at income, employment details, or other financial information. An accurate application may take a little longer, but it gives you a clearer basis for judging the result and reduces avoidable friction if the app asks you to review something.
A realistic everyday use case
Imagine that your car is needed for work, but a necessary repair appears several days before your paycheck. You have already checked your account, postponed a nonessential purchase, and confirmed that the next paycheck can cover the repayment without affecting rent or groceries. In that narrow situation, a fast advance could be useful because the problem is temporary and the repayment plan is visible.
My advice would be to use the app as the final step in that decision, not the first. I would compare the total repayment with the repair cost, ask whether the mechanic offers a payment arrangement, and check whether a bank overdraft or a trusted family arrangement would be less expensive. If PayDaySay remains the most practical option, I would borrow only the repair amount and save a reminder of the repayment date immediately after accepting.
Now change the scenario slightly: the same person is short every month and needs an advance to cover ordinary groceries before payday. That is a warning sign. The app may provide short-term relief, but repeated advances can create a cycle in which one paycheck is already committed before it arrives. In that case, a budgeting conversation, payment-plan request, nonprofit financial counselor, or more stable source of income support is likely to offer better long-term value.
Where the free access helps—and where it does not
Because the application itself is free, it is reasonable to install it and examine the borrowing flow before deciding. That is useful for someone who wants to understand the available process without committing to a paid download. The free entry point also makes it easier to keep the app available for a genuine emergency, although I would still prefer to review it before an emergency occurs so that I am not making a financial decision while stressed.
The key trade-off is that the app removes one access cost while leaving the borrowing decision intact. A free download can feel harmless, but an advance has real consequences. I would never judge value by the install price alone. I would judge it by whether the money solves a necessary, short-lived problem and whether the full repayment fits comfortably into the next budget.
This is also why I would be cautious with any offer that appears unusually convenient. Speed can be valuable when a payment deadline is close, but it can also shorten the time available for comparison. Before proceeding, I would take a screenshot or note of the final terms for my own records, then check that the amount and repayment schedule match what I intended. That habit is especially useful with any financial app where a single tap can move the process forward.
Practical strengths in the PayDaySay approach
The strongest aspect is focus. PayDaySay does not present itself as a sprawling financial suite; it is centered on the possibility of a payday advance. For someone who already understands the risks and needs to explore a short-term borrowing option, that narrow purpose can feel more useful than navigating a traditional banking app filled with unrelated tools.
Its compatibility is another practical advantage. Support for Android 6.0 and later means the app is not limited to people carrying the newest phones. That matters for users who keep an older device, use a budget handset, or do not want to replace working hardware just to investigate a financial service.
The public response is encouraging without being a substitute for reading the terms. A 4.6 average and a large body of ratings indicate that the app has earned positive reactions from many users. I see that as a reason to consider it, not as proof that every application will be approved or that every borrower will receive identical conditions. Personal eligibility and the specific offer remain more important than the overall score.
Another useful insight is that the app’s value depends heavily on timing. A person who has a confirmed paycheck arriving soon may use a small advance to bridge a genuine gap. Someone whose income date is uncertain has a much harder decision because the repayment plan may not align with reality. In other words, the same app can be reasonable for a predictable shortfall and unsuitable for unstable finances.
Limitations I would take seriously
The biggest limitation is not necessarily a missing button or a complicated screen; it is the nature of the product. Borrowing money quickly can encourage decisions based on urgency rather than affordability. The app can make the request convenient, but convenience does not make repayment easier. I would keep that distinction in mind throughout the process.
I would also avoid assuming that an application guarantees access to funds. A request for an advance may involve eligibility checks and an offer that does not match the amount imagined at the start. Treating the first screen as a promise is risky. I would only make plans around money after reviewing the actual outcome and its terms.
PayDaySay is not the right tool for building an emergency fund, tracking every category of spending, or comparing a broad range of financial products. A bank app may be better for reviewing account history and recurring payments. A budgeting app may be better for identifying why the shortfall keeps happening. A credit union or employer-based option may offer a more suitable route for some borrowers. The right alternative depends on the problem, but PayDaySay should not be forced into a role it was not designed to fill.
There is also a behavioral limitation that is easy to overlook: having an advance app on your phone can make borrowing feel like a normal part of monthly cash flow. I would reduce that risk by using it only for a clearly defined need, recording the repayment date, and removing access from my routine decision-making once the emergency has passed. The goal should be to solve one timing issue, not to turn borrowing into an automatic response to every tight week.
Who is most likely to get real value?
I think the app is most appropriate for an adult who needs to investigate a small, short-term cash gap, has predictable income, and can explain exactly how repayment will fit into the next budget. That person should be comfortable comparing the offer with other choices and willing to decline it if the total cost is too high.
It may also suit someone who values a straightforward mobile starting point and uses an older Android phone. The free installation makes it possible to review the service without paying to download it, while the Everyone rating keeps the app broadly accessible from an age-label perspective. Neither point removes the need for responsible borrowing, but both make the initial evaluation easier.
I would tell a friend to skip it if the request is for entertainment, an impulse purchase, or a recurring expense that has no reliable funding source. I would also skip it when repayment depends on an uncertain paycheck, when existing debts are already difficult to manage, or when another option offers clearer terms and a lower total cost. In those circumstances, speed is not enough to make the app good value.
One less obvious group that should be cautious is the person who has enough money overall but not enough in the current account because several automatic payments are scheduled close together. An advance might cover the immediate gap, but first I would review those payments, contact providers about changing dates, or move money between accounts if possible. Fixing the timing system can be better than borrowing to cover a timing system that will fail again.
My decision after weighing the trade-offs
After looking at it as a finance tool rather than a quick fix, I see Cash Advance Now - PayDaySay as a focused option for exploring a short-term payday advance, not a universal answer to financial pressure. Its free access, broad Android compatibility, and strong public rating make it worth examining when the need is genuine and repayment is predictable. The developer, PayDaySay, has kept the app’s identity closely tied to that single borrowing use case.
The current version is 1.26, and the app’s continued presence since its release gives it more context than a newly published finance tool. Still, version information and popularity should not decide whether you borrow. The decisive evidence is the offer presented to you: the amount received, the total repayment, the schedule, and whether that schedule leaves your essential budget intact.
My practical verdict is simple: install it only when you are prepared to compare, calculate, and possibly walk away. If the advance covers a necessary one-off expense and the repayment is comfortably supported by known income, PayDaySay may deliver useful value without an upfront app cost. If you are trying to fund normal living expenses, replace lost income, or borrow repeatedly, I would choose a longer-term financial solution instead.
Use it as a carefully checked bridge, never as proof that the underlying money problem has disappeared. That mindset captures both the app’s usefulness and its main risk. For the right emergency, it can be a convenient place to begin. For an ongoing shortage, it is better treated as a signal to seek a more sustainable answer.
Pros
- Simple application process with minimal paperwork required.
- May help cover urgent expenses before your regular payday.
- Clear repayment information can make costs easier to understand.
- Available online, avoiding the need to visit a physical lender.
- Useful for comparing potential loan offers in one place.
Cons
- Approval and loan availability may vary by state and eligibility.
- Fees and interest can make short-term borrowing expensive.
- Repayment deadlines may be difficult if your next paycheck is limited.
- Not intended as a long-term solution for recurring financial problems.
- Sharing personal and financial details may raise privacy concerns.
FAQs for Cash Advance Now - PayDaySay
What is Cash Advance Now - PayDaySay?
Cash Advance Now - PayDaySay is a financial service app designed to help users explore potential short-term loan or cash advance offers. After submitting personal and financial information, the app may connect you with third-party lenders or service providers. It is important to understand that the app itself may not be the lender, and approval, loan amounts, interest rates, fees, and repayment terms can vary depending on your profile and the provider available in your area.
How does the application process work?
The application process generally begins with a form requesting details such as your identity, income, employment, banking information, and contact data. The information may be used to evaluate eligibility or match you with participating lenders. Completing the form does not necessarily guarantee approval or funding. Before accepting any offer, carefully review the annual percentage rate, finance charges, repayment schedule, late-payment consequences, and the lender’s privacy and cancellation policies.
Is Cash Advance Now - PayDaySay safe to use?
Using a financial app requires extra caution because the application may handle highly sensitive personal and banking information. Before proceeding, verify that you are using the official listing, read its privacy policy, check the permissions it requests, and confirm which companies may receive your data. Never share passwords, security codes, or unnecessary account credentials. Also remember that third-party lenders may have separate terms, privacy practices, and security standards.
How much does a cash advance or loan cost?
The cost depends on the lender, your credit and income information, the amount borrowed, and the repayment period. Short-term borrowing can involve interest, origination charges, service fees, or other costs, and the annual percentage rate may be significantly higher than that of traditional credit products. Do not rely only on the advertised amount or payment estimate. Review the complete agreement and compare the total repayment amount before accepting an offer.
What should I consider before downloading and applying?
Before downloading Cash Advance Now - PayDaySay, consider whether borrowing is necessary and whether you can comfortably repay the balance on time. Check eligibility requirements, supported locations, minimum income rules, possible fees, and whether the service shares your information with marketing partners or lenders. A missed payment could lead to additional charges, collection activity, or credit consequences. Compare alternatives such as a bank, credit union, employer advance, or local assistance program.

Cash Advance Now - PayDaySay
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via contact@paydaysay.com, visit https://paydaysay.com/, or review their https://paydaysay.com/app-privacy.php.










